Investing
Freehold vs Leasehold Pubs: A Comparison for First-Time Buyers
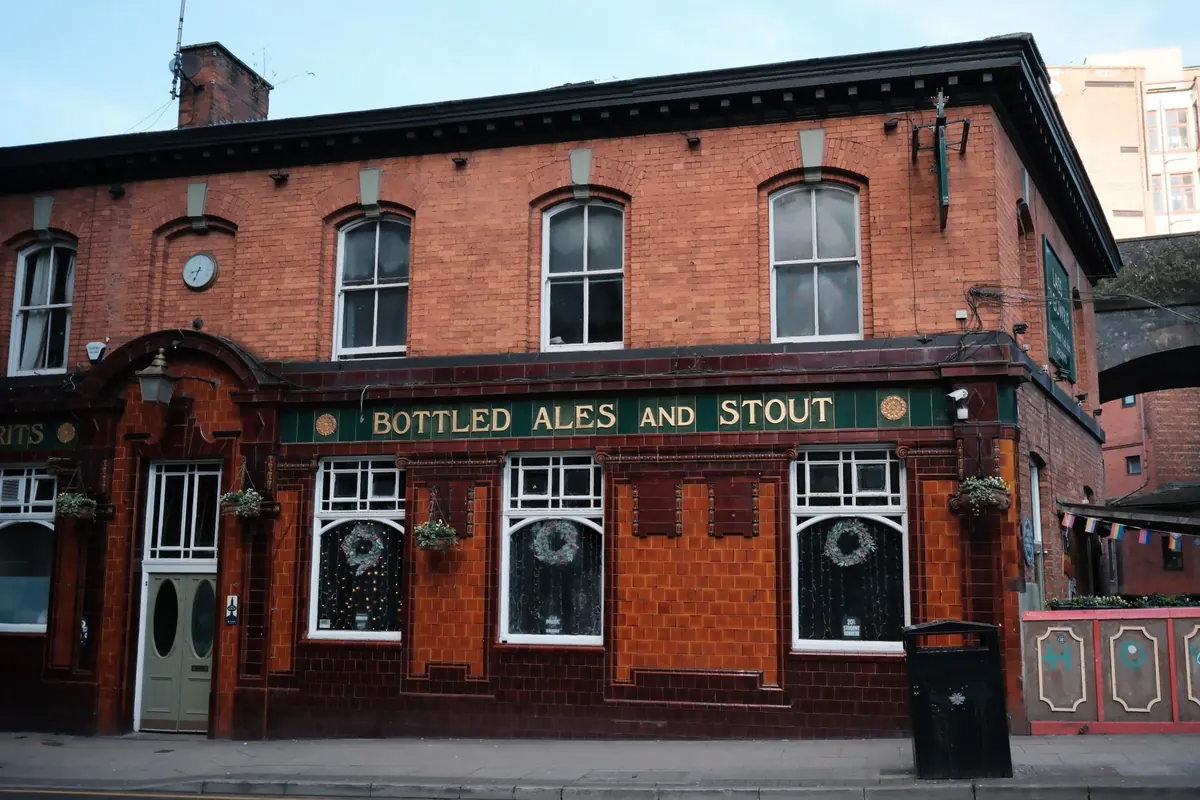
Two people can call themselves pub owners and mean completely different things. One holds the deeds to a building on the high street. The other holds a contract giving them the right to trade inside someone else's building for a set number of years. Both can be good businesses. Both can turn sour if you buy the wrong structure for your situation. Freehold or leasehold shapes what you pay up front, what you are allowed to change, what you owe every month, and what you walk away with.
The two structures, in plain terms
Freehold means you own the land and the building outright. You can sell it, let it, refurbish it, convert part of it, or pass it on to your family, subject to planning permission and licensing rules. Nobody can ask you to leave.
Leasehold means you buy a lease from the freeholder for a fixed term. You get the right to occupy and trade there until the term runs out, at which point the property reverts to the landlord unless you renew. On top of rent you will usually pay insurance, sometimes a service charge, and take on a repairing obligation.
Leases come in flavours. A tied lease requires you to buy beer and often other stock from the landlord or its nominated supplier. A free of tie lease lets you buy where you like, usually at a higher rent. Most leases sit somewhere between the two. Have a solicitor who deals in licensed premises read every clause before you commit.
Upfront cost: deeds versus premium
Freehold prices reflect the building, the location and the trading potential. You will need a larger lump sum, plus transaction taxes, legal fees, a survey, and money to cover whatever needs fixing before you open the doors.
Leasehold entry is cheaper. You may pay a premium for the lease, or nothing at all if the landlord is keen to get a tenant in. There is normally a rent deposit, a payment for fixtures, fittings and stock, and legal fees, often including the landlord's.
Here is the trap. A cheap lease with a high rent and a tied supply list can cost more over five years than a freehold bought with a mortgage. Compare the total cost of occupying the pub, not the price of getting through the door.
Costs that catch first-time buyers out:
- Transaction taxes. The way a deal is structured changes what is payable, so get advice before you agree a figure.
- Contents. Glassware, cellar equipment, tills, furniture and initial stock are rarely in the headline price.
- Immediate repairs. A survey on a freehold tells you what is wrong. On a leasehold, a schedule of condition tells you what you will have to hand back.
- Working capital. Budget for several months of wages, utilities and stock before the pub finds its rhythm.
- Professional fees. Solicitor, surveyor, valuer, licensing, accountant. They add up quickly.
Control: who decides what
On a freehold, you decide. Opening hours within your licence, the drinks range, whether you add food, letting rooms, a garden bar, a shop counter. You answer to the council, the licensing authority and your lender. Not to a landlord.
On a leasehold, you share decisions with the freeholder. Alterations need written consent. Assigning the lease needs consent. A tie dictates what you buy and from whom, which eats into margin. Some leases restrict opening hours or the kind of food you can serve.
The honest case for a lease
A good landlord is not just a cost line. Pub companies bring training, buying power, marketing support and a playbook for opening a site. If you have never run a pub, that scaffolding has real value. A freehold gives you freedom and little else. Nobody is coming to help when the cellar floods at eleven on a Friday night.
What you pay every month
Freehold: mortgage, buildings insurance, business rates, utilities, wages, licensing fees and repairs. No rent. Every big-ticket repair is yours, from the roof to the drains to the boiler. Build a maintenance reserve, because an old building always has something waiting.
Leasehold: rent, which is typically reviewed every three or five years; insurance rent; sometimes a service charge; and repairs, often under a full repairing and insuring obligation. That last point deserves attention. Unless a schedule of condition protects you, you can inherit years of disrepair as a bill when you leave.
Then there is the tie. Buying beer through the landlord's list at a premium is a monthly cost that never shows up in the rent figure.
The cheapest door into a pub is rarely the cheapest pub to run.
How lenders see each one
Freehold commercial mortgages are the mainstream route. Expect a substantial deposit, a term of perhaps ten to twenty-five years, and pricing linked to base rate plus a margin. Lenders will value both the property and the trading business, and want to see accounts and a realistic plan.
Leasehold lending is a narrower market. Some lenders avoid short leases altogether, and most want the remaining term to run comfortably past the end of the mortgage. Tied leases are harder still, because the lender can see how much of your gross profit goes to a supplier. Personal guarantees are common on both routes.
Exit: how you get your money back
Sell a freehold and you sell the building, with or without the business inside it. Buyers might be another operator, a developer, or someone who wants a house with a bar attached. The property value underpins everything.
Sell a leasehold and you sell the remaining term plus the goodwill. As the lease shortens, the price falls. You will need the landlord's consent to assign, and some leases entitle the landlord to a share of any premium. Dilapidations will need settling. Starting with twenty-five years and selling with eighteen left is a very different proposition from selling with six.
Business tenants in England and Wales may have statutory rights to renew, but those rights can be excluded by agreement. Read that clause carefully, and take legal advice on it before exchange, not after.
A practical way to choose
Work through these questions before you make an offer:
- How much capital will I have left after fees, stock and several months of working capital? If the freehold leaves you with nothing, it is the wrong answer right now.
- Do I want to be a property owner or a publican? They are different jobs, and both take time.
- Can I live with a tie? Model the supply cost against the rent saving across the whole term, not the first year.
- What does the exit look like in year ten, and who is the likely buyer?
- Has a solicitor who specialises in licensed premises read the lease, the schedule of condition and the tie agreement?
Neither route is better in the abstract. A lease with a fair rent and a supportive landlord can get you trading with money still in the bank. A freehold with a tired building can swallow your savings in the first winter. Match the structure to your capital, your experience and your appetite for risk, and take professional advice from a commercial solicitor, mortgage broker and accountant before you sign anything.
Photo: Pavel Danilyuk / Pexels
Related Articles